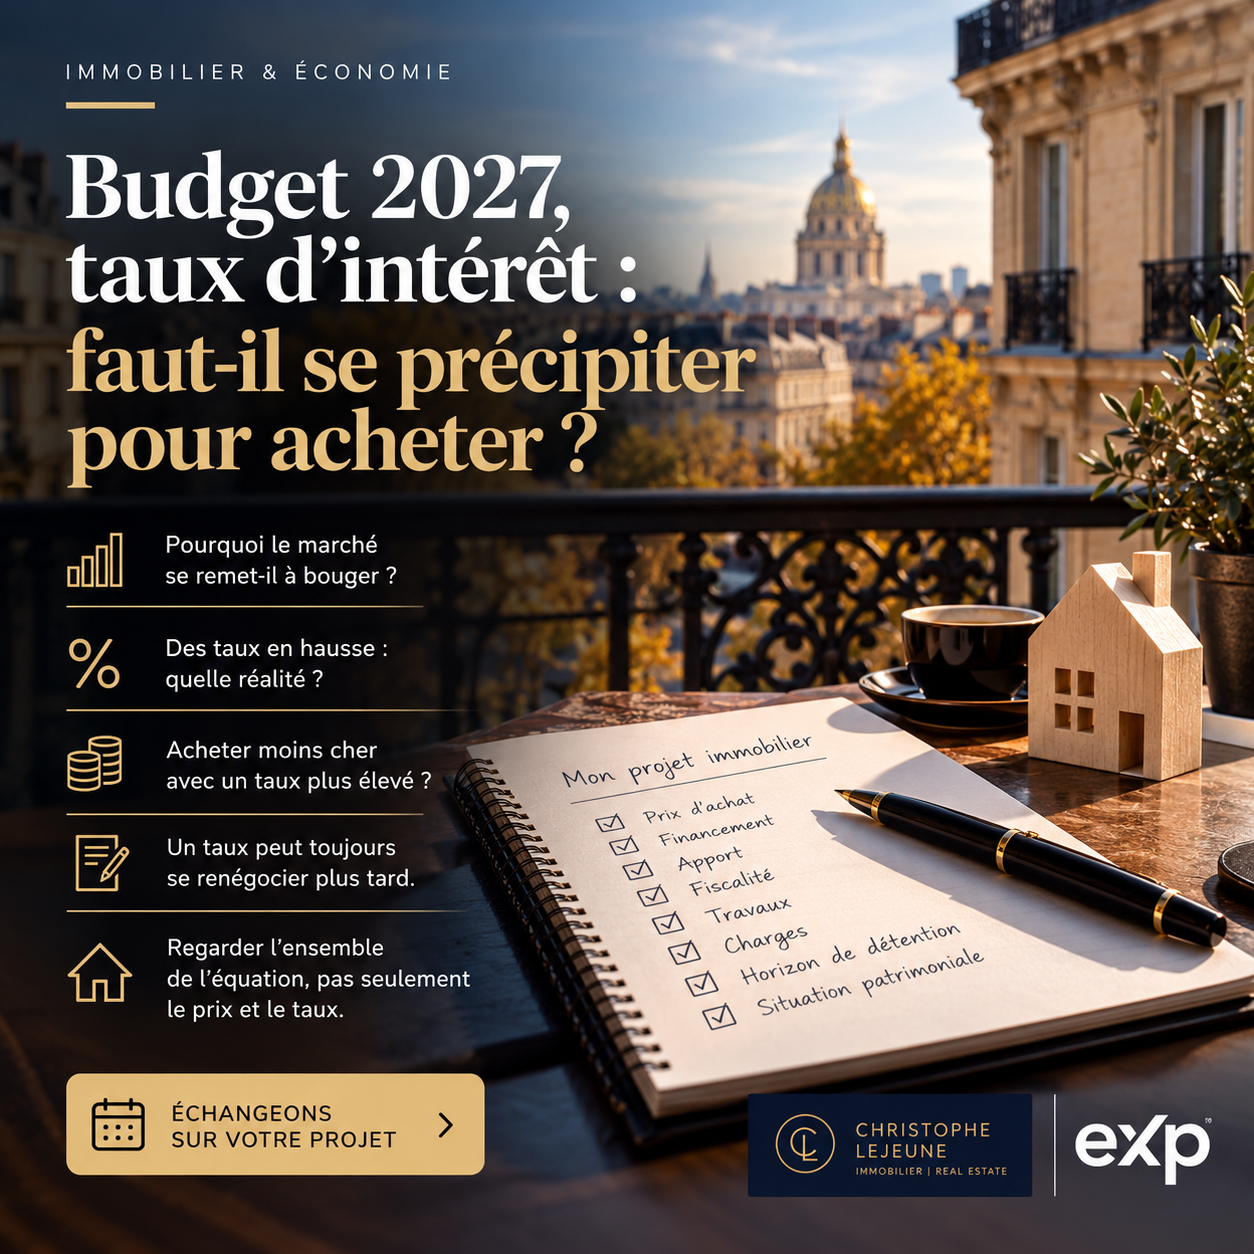
Real Estate: Should You Buy Before Interest Rates Rise Again?
Since the beginning of the academic year, I have observed an interesting development on the ground: demand is picking up and the number of qualified viewings is increasing noticeably.
This movement is occurring while financing conditions are tightening again.
As of October 1, 2026, the average rates observed by Pretto reach approximately 3.66% over 20 years and 3.75% over 25 years. At the same time, the yield on the French 10-year OAT has approached 5%, amid tensions in French debt financing.
The 2027 budget proposal presented on October 1 also includes 43 billion euros in new measures, with a goal of reducing the public deficit to 5% of GDP.
Should you buy now then?
This is probably the question some buyers are asking themselves.
The reasoning seems simple:
"If rates go up, it's better to buy before they increase further."
But in real estate, you must be wary of reasoning based on a single indicator.
Because another equation exists:
Buying at a lower price with a higher rate can sometimes be more advantageous than buying at a higher price with a lower rate.
Let's take a deliberately simplified example.
A property at €450,000 financed at 4% can be a more attractive transaction than a property at €500,000 financed at 3.5%, depending on the down payment, the loan term, and all costs related to the project.
This is obviously not to say that it is better to wait for a price drop or accept a rate increase.
It is about looking at the entire equation.
The rate is not the only parameter
Another element is sometimes overlooked: a mortgage is not necessarily fixed for the entire duration of the project.
If market conditions become more favorable, a borrower can, under certain conditions, renegotiate their loan or consider a refinance.
On the other hand, once the transaction is completed, the price at which the property was purchased cannot be renegotiated.
This is why I advise never making a decision based solely on the current rate.
You must consider:
the purchase price;
financing and down payment;
the affordable monthly payment;
taxation;
renovations;
expenses;
the holding period;
your family and financial situation;
and, for an investment, the expected return.
Buy quickly or buy right?
This is an important distinction.
The market can change.
Rates can go up or down.
Banks can modify their terms.
But your personal situation, your financial capacity, and the quality of the property remain decisive.
My advice is therefore simple: never rush because an indicator changes.
Before asking yourself:
"At what rate can I borrow?"
I prefer to ask another question:
"At what price and under what conditions does this purchase remain consistent with my project and my assets?"
This is also how I see the role of the real estate advisor today.
Not simply find a property.
But help make an informed decision.